LP
LANCE PENDLETON
For homeowners and families
Should I Sell My House at 65 or Stay? Here’s How to Actually Decide
Should I Sell My House at 65 or Stay? Here’s How to Actually Decide
Should I Sell My House at 65 or Stay? Here’s How to Actually Decide
By Lance Pendleton.
There is no single right answer to selling at 65 or staying. Write down what each one costs you, because until both numbers are on paper you are comparing one story to another.
This decision makes people go back and forth for months. Name what is pulling at you before you run the numbers, because a decision that is correct on paper can still feel wrong for years.
What you’ll walk away with:
What staying costs you every year, on a house that is paid off
What selling costs, and the federal exclusion that decides what you keep
Why feeling torn is information, and what to do with it
What to do if you’ve done the math and still can’t decide
Should I sell my house at 65, or is staying the smarter move?
Neither one is automatically smarter. A paid-off mortgage tells you nothing about what staying costs. A climbing market tells you nothing about what you keep after you sell.
I have spent 20 years training real estate agents, including the ones who sit across the table for this decision. The families who end up somewhere they do not regret start with a number on each side, then decide.
It’s your house, and it’s your decision. Not your kids’, not your neighbor’s who just downsized, not the agent’s who’d love the listing. One homeowner I’ll call Margaret spent three years being nudged toward selling by one adult child, while her other three each wanted something else. She wasn’t stuck on the math. She was stuck on who got a vote. The math never answers that question. Only she could, and she did, on her own timeline.
What staying costs.
Staying costs money every year, even on a paid-off house. The cost people skip is deferred maintenance.
Plan on 1.5% of your home’s current value per year: the roof, the heating system, the water heater, the driveway. None of it shows up as a monthly bill and all of it comes due. On a $450,000 house that is just under $7,000 a year, this year or the year the roof gives out.
Then add what the house will need over the next five years. Grab bars, a stair lift, a wider doorway, or in-home care at roughly $35 an hour. Once those are on the page, a paid-off house stops being a free house.
What selling costs, and what you keep.
Selling costs 8 to 12% of the sale price, once you count agent commission, closing costs and repairs. What you keep after that is decided by a federal tax rule, and it is rarely explained in plain language.
You can exclude up to $250,000 of the gain from federal tax if you are single, or $500,000 if you are married filing jointly. You have to have lived there for two of the last five years. The gain is not the sale price. Say you bought your home for $80,000 in 1975 and sold it today for $580,000. Your gain is $500,000. A married couple filing jointly could owe nothing on that at the federal level.
(This is general education, not tax advice. Take your own numbers to a CPA before you act on any of it.)
Still feeling torn after the math.
Yes, and the math was never going to settle that part. Grief is part of what it costs to leave a house you have lived in for decades. No spreadsheet talks you out of it, and none should.
A move at this stage of life rarely arrives on its own. It usually sits on top of a health change, or the loss of a spouse. Treat the house decision as if it stands alone and you will be exhausted for reasons that have nothing to do with square footage.
The feeling does not have to be resolved before you decide. Say it out loud to someone if you can, and make the choice anyway. If you wait for the sadness to lift, the decision gets made for you, usually on worse terms.
This article covers how to think about it. The Senior Partner, homeowner edition, has the worksheets, the same math broken into six parts, and the questions to ask an agent who does this work. Chapter One is free by email.
How to decide.
You decide by putting both numbers on paper, sitting with them for an hour, and running them again in two years. Certainty is not part of it.
Write your home’s current estimated value on one line. Add the last twelve months of costs you can see, then the 1.5% for deferred maintenance. On the other side, the 8 to 12% selling cost and the Section 121 math. Then sit with both numbers for an hour, with nobody else in the room.
Put a date on the calendar two years out to run it again. Your health and your home’s value will both have moved. The house isn’t going anywhere in the meantime, and neither is your right to decide.
Frequently Asked Questions
Is 65 too old to sell a house and downsize?
No. The same tax rules and the same logistics apply at 65 or 85 as at 45.
How much does it cost to sell a house after age 65?
Selling costs 8 to 12% of the sale price, once you count agent commission, closing costs and repairs. That range is the same at any age.
Do I have to pay capital gains tax if I sell my house after 65?
Not on the full gain, in most cases. If you have lived in the house for two of the last five years, you can exclude up to $250,000 of gain if single, or $500,000 if married filing jointly, under IRS Section 121.
Is staying in my home as I get older a bad financial decision?
Not automatically. Staying costs roughly 1.5% of home value per year in deferred maintenance, which can still be less than the cost and the disruption of moving.
What’s the right age to downsize a home?
There isn’t one. Running both costs every couple of years is a better trigger than any age.
Why the hour is worth it.
You get to make this one on your own terms, with both numbers in front of you instead of a story somebody handed you. That is worth the hour it takes to write the numbers down.
If you want to talk through your own numbers before you talk to an agent, The Senior Partner Call is free, by phone, and takes about half an hour. You tell me what is going on and I tell you how it usually goes. There is nothing to buy on it. Pick a time that suits you.
Where the numbers come from
The federal home sale exclusion is up to $250,000 of gain, or up to $500,000 on a joint return. You must have owned the home and lived in it for two of the last five years. IRS Topic No. 701, Sale of Your Home, reviewed September 2026.
Fannie Mae’s rule of thumb for upkeep is 1% to 4% of a home’s value per year, leaning toward 4% once a house is more than 30 years old. The 1.5% I use sits inside that range. Fannie Mae, How to Build Your Maintenance and Repair Budget, read October 2026.
Freddie Mac puts real estate commission at 3% to 8% of the sale price and fees and taxes at 2% to 4%, with repairs on top. The 8 to 12% I use is a planning range built from those parts. Freddie Mac, Understanding the Costs of Selling Your Home, read October 2026.
The national median cost of a non-medical caregiver at home was $35 an hour in 2025, up from $34 in 2024. CareScout Cost of Care Survey, 2025.
Figures checked October 2026.
This is general education. It is not tax, legal or financial advice.
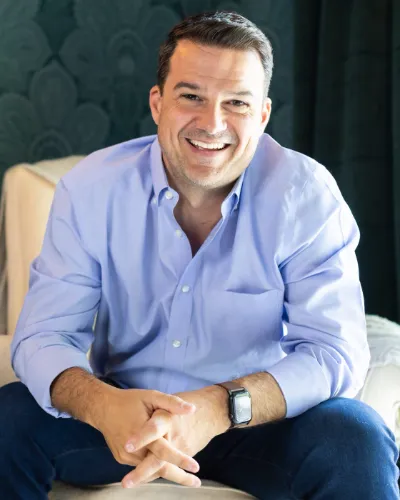
Lance Pendleton is a real estate coach, TEDx speaker and author of The Senior Partner, based in Connecticut.
He founded PreTSD Consulting, created Reframe Lab and was National Head of Agent Development at Compass. Who you will be talking to
Read the first chapter.
Read the first chapter.
Chapter One of The Senior Partner, homeowner edition, free by email.